
Mining Insurance in Queensland: What Mining Contractors Need to Be Covered (2026 Guide)
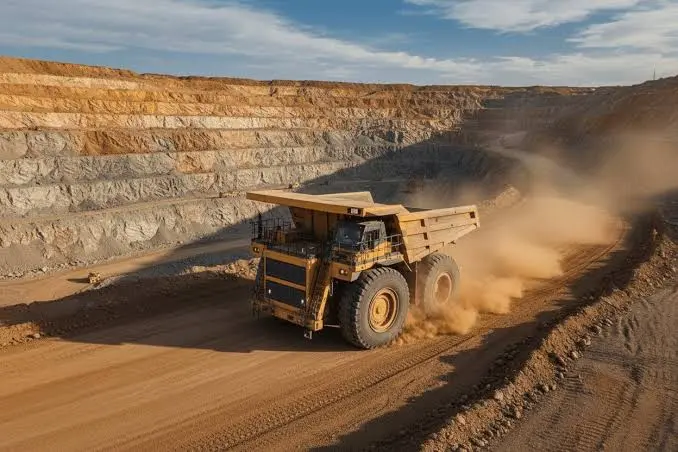
Queensland’s mining industry runs on contractors. From drilling crews in the Bowen Basin to maintenance teams in Mount Isa and haulage operators across the North West Minerals Province, contractors keep mine sites moving every day. But before you set foot on a site, the mine operator will ask one question: are you properly insured?
The wrong cover can cost you a contract, and a gap in your policy can cost you your business. This guide explains which insurance mining contractors in Queensland need, what mine operators expect, and how to avoid the mistakes that leave contractors exposed.
Why Mining Contractors Need Specialist Insurance
Mining is one of the highest-risk industries in Australia. Heavy machinery, explosives, remote locations, underground work and strict safety laws all combine to create risks that standard business insurance often won’t cover.
Many off-the-shelf liability policies exclude underground work, work on mine sites, or damage caused by blasting and excavation. If you buy a generic tradie policy and then take a job on a mine site, you may find you have no cover at all when you need it most.
Mine operators know this. That’s why most site contracts set out strict insurance requirements, and many principals won’t let you start work until they’ve checked your certificates of currency.
Who Needs Mining Insurance?
Mining insurance suits any business that works on or supplies Queensland mine sites, including:
- Drilling and blasting contractors
- Earthmoving and civil contractors
- Haulage and transport operators
- Mechanical and electrical maintenance contractors
- Labour hire companies supplying mine site workers
- Engineers, geologists, surveyors and consultants
- Equipment hire and plant suppliers
- Shutdown and fabrication crews
Whether you run a one-person operation or a fleet of 50 machines, your insurance needs to match the work you actually do on site.
The Key Types of Cover for Mining Contractors
Public and Products Liability Insurance
Public liability insurance is the foundation of any mining contractor’s insurance program. It covers your legal liability if your work injures someone or damages property belonging to the mine operator or a third party. Products liability extends that protection to goods you supply, install or repair.
Mine operators commonly require high limits of liability, often $20 million or more, and some major sites ask for higher. Always check your contract before you choose a limit. Just as importantly, make sure your policy specifically covers mining activities and underground work if your job involves them. Our public liability insurance page explains this cover in more detail.
Contractors Plant and Equipment Insurance
Your machinery is your livelihood. Excavators, drill rigs, loaders, dozers and generators represent a huge investment, and mine sites expose them to constant wear, rollover, fire, collapse and theft.
Plant and equipment insurance covers your machinery against accidental damage, fire and theft, both on site and in transit. You can also add hire-in plant cover if you regularly hire equipment from others, because the hire contract usually makes you responsible for any damage.
Commercial Motor and Fleet Insurance
Utes, service trucks, light vehicles and haul trucks all need commercial motor cover. Vehicles on mine sites face different risks from those on public roads, so tell your insurer where and how you use each vehicle. A fleet policy can simplify things if you run several vehicles. Learn more on our truck and transport insurance page.
Workers’ Compensation
If you employ workers in Queensland, you must hold a WorkCover Queensland policy unless you’re a licensed self-insurer. This cover pays for your workers’ medical costs and lost wages if they’re injured at work. Mine operators will ask for proof of your WorkCover policy before your team can start.
Personal Accident and Illness Insurance
WorkCover doesn’t cover sole traders and business owners who aren’t employees. If you run your own rig and an injury stops you working, personal accident and illness insurance can replace part of your income while you recover. Read more about personal accident and illness insurance.
Professional Indemnity Insurance
If you give advice or design work, such as engineering, geotechnical assessments, surveying or safety consulting, you need professional indemnity insurance. It protects you if a client claims your advice or design caused them a financial loss. Many mining contracts require PI cover for consultants, so check your agreement carefully.
Environmental and Pollution Liability
Standard public liability policies usually cover only sudden and accidental pollution. They often exclude gradual contamination, such as a slow fuel or chemical leak. Given Queensland’s strict environmental laws, contractors who handle fuel, chemicals or waste should consider dedicated environmental impairment cover.
Business Interruption Insurance
If a fire destroys your workshop or your key machine breaks down, your income can stop overnight. Business interruption insurance helps cover lost profits and ongoing expenses while you get back up and running. For North Queensland contractors, this cover also matters during the cyclone and wet season, when weather can shut down operations.
What Mine Operators Expect From Contractors
Before you sign a mining contract, read the insurance clause carefully. Mine operators often require contractors to:
- Hold minimum liability limits that match the contract
- Name the principal as an interested party on the policy
- Include a waiver of subrogation in the principal’s favour
- Provide certificates of currency before work begins
- Keep cover in place for the full contract term
- Notify the principal if the policy changes or cancels
Contracts also often include indemnity clauses that make you responsible for losses beyond what the law would normally require. Your insurance may not cover every liability you accept under contract, so a broker should review these clauses before you sign.
Common Mistakes Mining Contractors Make
Choosing the cheapest policy. A low premium often means narrow cover. The cheapest policy may exclude mining, underground work or the exact activity you do.
Underinsuring machinery. Many contractors insure their plant for what they paid years ago, not what it costs to replace today. If you underinsure, your insurer may pay only part of your claim.
Not updating the insurer. If you take on new types of work, move to a new site or buy new equipment, tell your insurer. Undisclosed changes can lead to declined claims.
Overlooking sole trader income. Many owner-operators assume WorkCover protects them. It usually doesn’t, which leaves them with no income if they’re hurt.
Signing contracts without checking insurance clauses. Some contract requirements are expensive or impossible to meet with a standard policy. Check first, sign second.
What Affects the Cost of Mining Insurance?
Insurers look at several factors when they price your cover, including:
- The type of work you do, and whether it’s above or below ground
- The value and age of your plant and equipment
- Your annual turnover and wage roll
- The liability limits your contracts require
- Your claims history and safety record
- The locations and sites you work on
A strong safety record and documented safety management systems can help you secure better terms, because insurers reward contractors who manage risk well.
How a Broker Helps Mining Contractors
Mining insurance is complex, and no single policy fits every contractor. An insurance broker works for you, not the insurer. At Townsville Insurance Brokers, we:
- Review your contracts and site requirements
- Compare quotes from multiple insurers that understand mining risks
- Identify gaps and exclusions before they become problems
- Arrange certificates of currency quickly so you can start work on time
- Support you through the claims process if something goes wrong
Because we’re based in Townsville, we understand the risks North Queensland contractors face, from remote site work to cyclone season.
Frequently Asked Questions
Is public liability insurance mandatory for mining contractors in Queensland?
The law doesn’t require it for every business, but almost every mine operator requires it in their contracts. In practice, you can’t work on most Queensland mine sites without it.
How much public liability cover do I need for a mine site?
It depends on your contract. Many mine operators ask for $20 million, and some require more. Always check your contract before you buy.
Does my standard business insurance cover mining work?
Often it doesn’t. Many standard policies exclude mining, underground work or blasting. Check your policy wording or ask a broker to review it.
Can I insure hired equipment?
Yes. Hire-in plant cover protects equipment you hire from others, which matters because most hire agreements make you liable for damage.
Get the Right Mining Insurance Today
Don’t wait until a mine operator rejects your certificate or an insurer declines your claim. Talk to Townsville Insurance Brokers today. We’ll review your work, your contracts and your equipment, then compare options to find cover that fits.
Call us on 1300 270 772 or request a free quote online.
General Advice Warning: Any advice provided is general in nature and does not take into account your objectives, financial situation or needs. You should consider whether it is appropriate for you and read the relevant Product Disclosure Statement/Policy Wording before making any decision.
Subscribe to our newsletter
Related posts
More Blog Posts
Steel Fabricator & Manufacturing Insurance in QLD: Covers, Risks and Costs Explained
Mining Insurance in Queensland: What Mining Contractors Need to Be Covered (2026 Guide)
Is Professional Indemnity Insurance Mandatory in Australia? Requirements by Profession (QLD 2026)
Does Home Insurance Cover Flood in Queensland? Storm vs Flood vs Storm Surge Explained (2026 Guide)
Strata Insurance Townsville: Why Premiums Are High and How Body Corporates Can Reduce Them
Cyclone Season Checklist for Townsville Homeowners: Review Your Insurance Before November
What Does Public Liability Insurance Cover in Australia?
How Much Does Business Insurance Cost in Australia? A Complete Guide for Small Businesses
How Much Does Home Insurance Cost in Townsville, QLD?
Boat Insurance QLD: Compare Cover for Boats, Yachts & PWCs
Heavy Motor, Semi-Trailer & Trailer Insurance in Queensland

Apartment & Renters Insurance in Australia | Townsville Insurance Brokers

Landlord Insurance QLD | Landlord Policy Insurance Quote | Townsville Insurance Brokers
Caravan Insurance Australia: What It Covers, What It Costs, and How to Choose the Right Policy

Combined Truck & Trailer Insurance Australia | Guide

Truck Insurance in Australia: What You Actually Need to Know?

How Insurance Protects the Mining Industry from Risk and Disruption

10 Reasons to Get Commercial Truck Insurance in QLD

Truck and Trailer Insurance in Townsville: Cover Options, Costs and How to Choose


GRX Event 2025

Small Business Risk Management: 6 Proven Strategies to Protect Your Business

Mining Contractor Insurance: Why Contractors Arrange Their Own Cover


Professional Indemnity Excess Layer Insurance for Australian Businesses


Licensed Venue Insurance in Queensland: What Pubs, Bars and Restaurants Need

Transport sector insurance


Types of Business Insurance in Australia: What Your Business Actually Needs

Get In Touch With Us
Have questions about Insurance? We're here to help!