
Does Home Insurance Cover Flood in Queensland? Storm vs Flood vs Storm Surge Explained (2026 Guide)
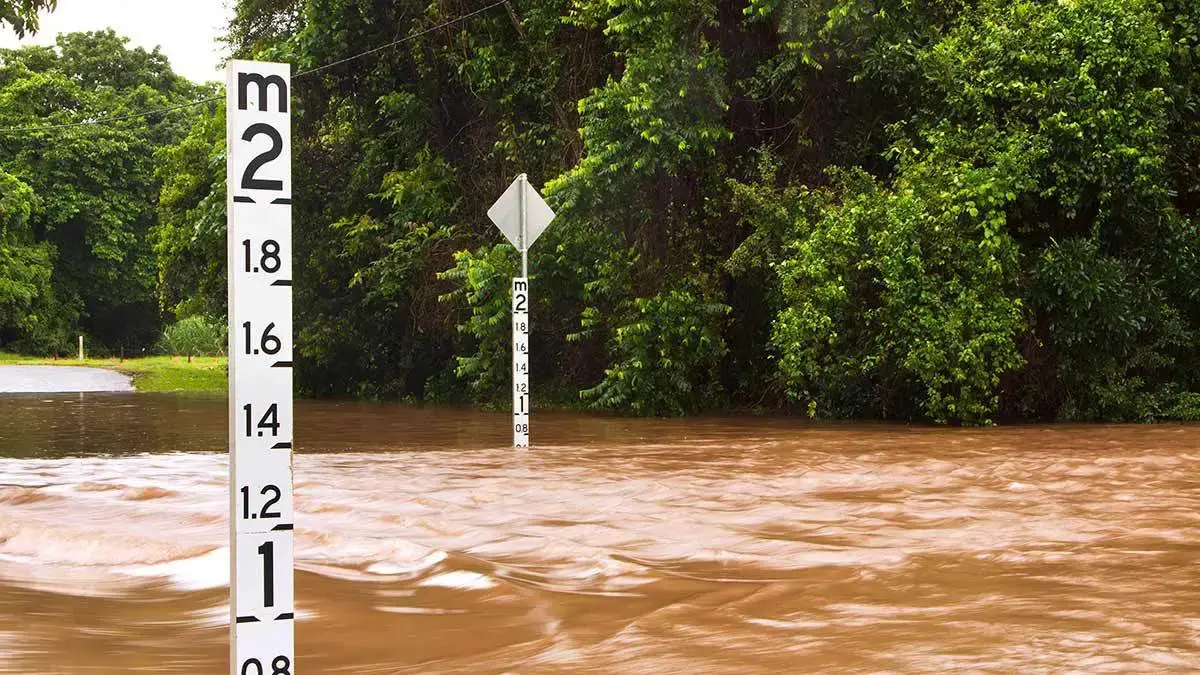
Does home insurance cover flood in Queensland? Often yes, but not always. Many home and contents policies in Queensland include flood cover as standard, others offer it as an optional extra, and some let you remove it to lower your premium. Storm damage is usually covered automatically, while storm surge is commonly excluded. A single cyclone can cause all three types of damage, so you need to know exactly what your policy says before the wet season arrives.
Townsville residents know this better than most. The 2019 monsoon floods damaged thousands of homes across the city, and many owners learned the hard way that “storm” and “flood” mean very different things to an insurer. This guide explains how flood insurance works in QLD, what it costs, what it excludes, and how to check your own policy in a few minutes.
Does Home Insurance Cover Flood? The Short Answer
Home insurance covers flood only if your policy includes flood as an insured event. Here are the three common setups in Queensland:
- Flood included as standard: The policy covers flood automatically.
- Flood as an optional extra: You pay an extra premium to add it.
- Flood excluded or opted out: The policy doesn’t cover flood at all, though it usually still covers storm damage.
Don’t assume you’re covered. Open your Product Disclosure Statement (PDS) and your Certificate of Insurance and look for the word “flood” in the list of insured events.
What Counts as a Flood Under Australian Home Insurance?
After the 2011 Brisbane floods, the Australian Government introduced a standard flood definition. Insurers that offer flood cover must now use the same wording.
Under this definition, a flood is the covering of normally dry land by water that escapes or is released from the normal confines of a lake, river, creek or other natural watercourse, or from a reservoir, canal or dam.
Because the definition is standard, flood cover works the same way regardless of which insurer you choose. What does differ between insurers is the price, the excess, the sum insured and the extra benefits.
Storm vs Flood vs Storm Surge: What’s the Difference?
This is where most claim disputes start. The table below compares the three events.
Event
What it usually means
Typically covered?
Storm
Wind, rain, hail or cyclone damage, such as a damaged roof, fallen trees or rain entering through a broken window
Yes, in most policies
Flood
Water escaping a creek, river, lake, dam or other watercourse and covering normally dry land
Only if flood is included or added
Storm surge / actions of the sea
Seawater pushed inland by a cyclone, or tides and waves
Commonly excluded
Rainwater runoff sits in a grey area. This is water flowing over the ground during heavy rain, without coming from a watercourse. Some insurers cover it under storm, while others treat it differently. Check your PDS for the exact wording.
Here’s a real-world example. A cyclone tears off your roof and rain soaks your ceilings. That’s storm damage. The next day, the nearby creek overflows and water fills your ground floor. That’s flood damage. If you don’t have flood cover, your insurer can pay for the roof and ceilings but decline the ground-floor claim.
Does Home Insurance Cover Flood in Townsville? Lessons From 2019
The February 2019 floods showed exactly why this matters in North Queensland. Record rainfall forced the release of water from the Ross River Dam, and suburbs such as Hermit Park, Idalia, Rosslea and Railway Estate went under.
The Insurance Council of Australia declared the event a catastrophe. Its CEO noted at the time that, nationally, about 94% of home building and contents policies sold included flood cover. Owners who had opted out of flood had their claims tested against the standard definition.
Three lessons for Townsville homeowners:
- Know your flood overlay. Check the Townsville City Council flood mapping for your address.
- Don’t remove flood cover to save money unless you understand the risk.
- Review your sum insured. Rebuilding costs in North Queensland rise sharply after major events.
How Much Does Flood Insurance Cost in QLD?
Insurers rate home insurance by risk, so your flood premium depends on how likely your home is to flood. If you live in an apartment on high ground, flood cover adds very little. If your house sits near a creek or river, it can add hundreds of dollars or more each year. In flood-affected parts of Queensland, adding flood cover can more than double the cost of a home and contents policy.
The main factors that affect your premium:
- Your home’s elevation and distance from watercourses
- Your suburb’s flood history and council flood mapping
- Your building type, raised or slab-on-ground
- Your sum insured and chosen excess
- Any flood mitigation work, such as raised floors or flood-resilient materials
The Australian Government’s Cyclone Reinsurance Pool also aims to ease premiums in cyclone-prone areas of northern Australia, including Townsville, so it’s worth asking whether your insurer passes on those savings.
What Flood Insurance Usually Doesn’t Cover
Even with flood cover, common exclusions include:
- Storm surge and actions of the sea
- Waiting periods: Many policies don’t cover a flood within the first 48 to 72 hours of a new policy or increased cover.
- Gradual damage: Rising damp, long-term seepage or poor drainage
- Mould caused by delays: Insurers may decline mould if you didn’t dry the property promptly.
- Vehicles: Your car needs comprehensive motor insurance. Home and contents insurance won’t cover it.
- Embargo periods: Insurers typically stop selling new cover once a flood or cyclone warning is issued.
How to Check If Your Policy Covers Flood
Take 10 minutes and work through these steps:
- Find your Certificate of Insurance and check whether “flood” appears as an included event.
- Read the PDS definitions for flood, storm, rainwater runoff, storm surge and actions of the sea.
- Check for any opt-out. If you removed flood cover at renewal to save money, it won’t apply.
- Confirm your sum insured matches today’s rebuild cost, not your purchase price.
- Look for extra benefits like temporary accommodation, debris removal and contents storage.
- Ask a broker to compare your cover against other insurers if anything is unclear.
Flood Cover for Landlords, Unit Owners and Renters
Landlords: Make sure your [landlord insurance] covers flood for the building and includes loss of rent while repairs happen.
Unit owners: Your body corporate’s [strata insurance] covers the building, but you need your own contents cover. Ask for the strata certificate of currency to confirm whether it includes flood.
Renters: Your landlord’s policy doesn’t protect your belongings. You need your own contents insurance with flood cover.
Frequently Asked Questions
Is flood cover automatic in Queensland home insurance?
No. Some policies include it as standard, some offer it as an option, and some exclude it. Always check your policy.
Does home insurance cover flood damage from a cyclone?
It covers cyclone-related flood damage only if your policy includes flood. Wind and rain damage usually falls under storm cover.
Is storm surge covered by home insurance?
Usually not. Most Australian home insurance policies exclude storm surge and actions of the sea.
Can I buy flood insurance when a flood warning is issued?
Generally no. Insurers usually place embargoes on new cover once a warning is issued, and many apply waiting periods.
Does contents insurance cover flood?
Only if flood is an insured event in your contents policy. Check it separately from your building cover.
Get Your Flood Cover Checked Before the Wet Season
Does home insurance cover flood for your Queensland home? The only way to know for sure is to check your policy now, before the wet season and cyclone season begin. Once a warning is issued, it’s usually too late to change your cover.
At Townsville Insurance Brokers, we’re locals. We understand North Queensland’s flood and cyclone risks, and we compare cover from multiple insurers to find the right protection for your home. Read our [cyclone season insurance checklist] or call 1300 270 772 for a free review today.
General Advice Warning: Any advice provided is general in nature and does not take into account your objectives, financial situation or needs. You should consider whether it is appropriate for you and read the relevant Product Disclosure Statement/Policy Wording before making any decision.
Subscribe to our newsletter
Related posts
More Blog Posts
Is Professional Indemnity Insurance Mandatory in Australia? Requirements by Profession (QLD 2026)
Does Home Insurance Cover Flood in Queensland? Storm vs Flood vs Storm Surge Explained (2026 Guide)
Strata Insurance Townsville: Why Premiums Are High and How Body Corporates Can Reduce Them
Cyclone Season Checklist for Townsville Homeowners: Review Your Insurance Before November
What Does Public Liability Insurance Cover in Australia?
How Much Does Business Insurance Cost in Australia? A Complete Guide for Small Businesses
How Much Does Home Insurance Cost in Townsville, QLD?
Boat Insurance QLD: Compare Cover for Boats, Yachts & PWCs
Heavy Motor, Semi-Trailer & Trailer Insurance in Queensland

Apartment & Renters Insurance in Australia | Townsville Insurance Brokers

Landlord Insurance QLD | Landlord Policy Insurance Quote | Townsville Insurance Brokers
Caravan Insurance Australia: What It Covers, What It Costs, and How to Choose the Right Policy

Combined Truck & Trailer Insurance Australia | Guide

Truck Insurance in Australia: What You Actually Need to Know?

How Insurance Protects the Mining Industry from Risk and Disruption

10 Reasons to Get Commercial Truck Insurance in QLD

Truck and Trailer Insurance in Townsville: Cover Options, Costs and How to Choose


GRX Event 2025

Small Business Risk Management: 6 Proven Strategies to Protect Your Business

Mining Contractor Insurance: Why Contractors Arrange Their Own Cover


Professional Indemnity Excess Layer Insurance for Australian Businesses


Licensed Venue Insurance in Queensland: What Pubs, Bars and Restaurants Need

Transport sector insurance


Types of Business Insurance in Australia: What Your Business Actually Needs

Get In Touch With Us
Have questions about Insurance? We're here to help!