
Mining Contractor Insurance in North Queensland: Covers, Contract Requirements and Costs
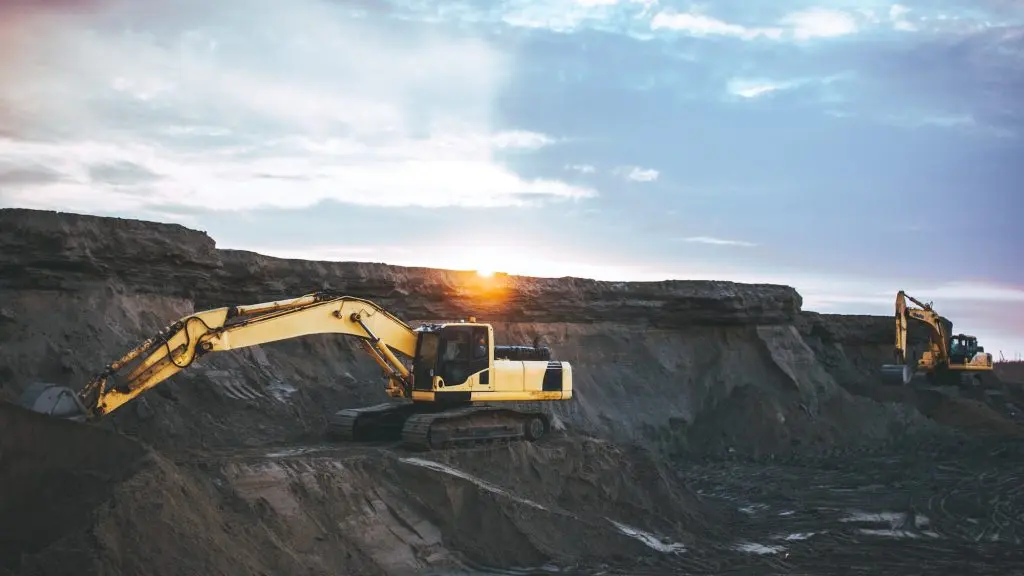
You’ve won the contract, your crew is ready and the mobilisation date is set. Then the site’s contractor management team asks for your certificates of currency, and one of your policies doesn’t meet their minimums. This happens to North Queensland contractors more often than it should, and it can delay or even cost you the job.
This guide explains which insurance mine sites usually expect from contractors, the exclusions that catch businesses out, what drives your premium, and how to get site-ready before you mobilise. It’s written for diesel fitters, boilermakers, electricians, drillers, earthmovers, haulage operators, labour hire firms and the other trades that keep the region’s mines running.
Why Mining Contractors in North Queensland Need Specialist Insurance
Contractors make up a big part of the regional mining workforce. In the North West region alone, around 7 in 10 resource industry workers in June 2023 were employees (6,150 people), and the remaining 2,510, or 29%, were contractors. Many of these businesses are based in Townsville and travel to sites across the North West Minerals Province, Charters Towers and the Bowen Basin. qgso
Mine sites carry heavy plant, high-voltage equipment, explosives, remote locations and strict safety regimes. Insurers price that risk differently from ordinary trade work. A standard tradie policy that works well for residential jobs often falls short once you step onto a mining lease.
What Insurance Do Mine Sites Require From Contractors?
Every mine operator sets its own requirements in the contract, so always read the insurance clause before you sign. That said, most sites ask for a similar core set of covers.
Public and Products Liability
This is the cover every site checks first. It protects you if your work injures a third party or damages someone else’s property. $20 million is the common benchmark. For example, Glencore states that contractors working on site will generally need $20 million in public liability insurance, and may also need professional indemnity insurance depending on the work. glencore
If your current policy carries a $5 million or $10 million limit, you’ll likely need to increase it before you start. Some head contracts also require the principal to be noted as an interested party on your policy, so check for that wording too.
Workers’ Compensation (WorkCover Queensland)
All Queensland-based employers who employ workers must insure them against work-related injury or illness, and all PAYG workers and some contractors are generally considered workers. If you employ anyone, a WorkCover policy is a legal requirement, and sites will ask for proof. worksafe
Subcontractors need care here. Whether someone you engage counts as a “worker” depends on the arrangement, not just their ABN. If you get this wrong, you can end up with an uninsured injury on site. WorkCover Queensland’s website provides practical steps to help you work out whether a contractor counts as a worker. marsh
Plant and Equipment Insurance
Excavators, loaders, service trucks, generators, welders and drill rigs are expensive to replace and hard to work without. Plant and equipment insurance covers damage, theft, fire and rollover. Cover can range from a contractor’s few thousand dollars of power tools to fleets worth hundreds of thousands. australianminingreview
If your gear goes underground, tell your broker. Many plant policies exclude loss of or damage to plant and machinery working underground unless otherwise agreed by endorsement. sgic
Commercial Motor and Fleet Insurance
Utes, service vehicles and trucks travelling between Townsville and remote sites rack up serious kilometres on rough roads. Fleet cover protects your vehicles and covers your liability on the road. Be aware that many standard motor vehicle policies contain exclusions for work carried out on a mining site. Our truck insurance team can check your fleet wording. australianminingreview
Professional Indemnity Insurance
If you give advice, design, certify, survey or consult, the site may ask for professional indemnity cover. Engineers, geologists, surveyors and safety consultants need it most. See our professional indemnity insurance page for details.
Personal Accident and Illness Cover
Sole traders and owner-operators usually can’t claim WorkCover for themselves. If an injury keeps you off the tools for weeks, your income stops. Personal accident and illness insurance pays a weekly benefit while you recover.
Policy Exclusions That Catch Mining Contractors Out
Holding a $20 million certificate doesn’t mean you’re covered for mining work. These are the exclusions we see most often.
Mining activity exclusions. Some public liability policies cover work on mine sites, but not work that relates to the mining activities themselves. So electrical work in the accommodation areas may be covered, while electrical work on mining equipment may not. australianminingreview
Underground work exclusions. Some liability policies exclude work or accidents inside underground mines, as well as work that directly supports mining, such as tunnels, shafts or heavy equipment used below ground. If you work underground at sites like Mount Isa or Cannington, you need a policy that specifically allows it. upcover
Coal sector restrictions. Many insurers have pulled back from coal. Brokers have reported that businesses linked to coal mining face soaring premiums and difficulty getting cover, with the issue reaching mining assets, professional indemnity for engineers and vehicle fleet insurance. If you service coal mines in the Bowen or Galilee basins, approach the market early. insurancenews
Contractual liability. Head contracts often ask you to indemnify the mine operator beyond what the law would normally require. Standard policies may not cover that extra liability, so check the indemnity clause with your broker before you sign.
How Much Does Mining Contractor Insurance Cost?
There’s no single price, because two contractors in the same trade can pose very different risks. Insurers usually look at:
- Your trade and the work you do on site. Blasting, underground work, hot work and drilling cost more to insure than cleaning or catering.
- Liability limit. A $20 million limit costs more than $5 million or $10 million.
- Turnover and wages. Higher turnover and bigger payrolls increase the premium.
- Commodity. Coal work can attract higher premiums and fewer willing insurers.
- Plant value and age. Expensive or older machinery affects your plant premium.
- Claims history and safety systems. A clean record and documented safety management systems help you negotiate better terms.
- Excess. Choosing a higher excess can lower your premium, but make sure you can afford it if you claim.
The best way to control cost is to insure the work you actually do. Paying for cover you don’t need wastes money, and leaving out an activity can void a claim.
Getting Site-Ready: A Pre-Mobilisation Insurance Checklist
Before you mobilise, work through this list:
- Read the insurance clause in the head contract and note every required cover and limit.
- Confirm your public liability limit meets the site minimum, usually $20 million.
- Check that your policy covers mining activities and, if relevant, underground work.
- Make sure your WorkCover policy is current and covers everyone who counts as a worker.
- List every item of plant going to site and confirm values and underground cover.
- Check that your vehicle policy doesn’t exclude mine site use.
- Ask your broker to issue certificates of currency that name the principal if required.
- Set renewal reminders so your cover doesn’t lapse mid-contract.
How a Townsville Insurance Broker Helps Mining Contractors
A broker works for you, not the insurer. We read the head contract, compare wordings from several insurers, and find a policy that matches the site’s requirements and the work you actually perform. When a site rejects a certificate, we sort it out quickly so you don’t lose mobilisation days. If something goes wrong, we handle the claim with you from start to finish.
Learn more on our mining insurance page, or call 1300 270 772 for a free quote.
Mining Contractor Insurance FAQs
Do all mine sites require $20 million public liability?
Not every site, but $20 million is the most common requirement in Queensland. Some smaller sites or short jobs may accept a lower limit, so always check your contract.
Does my tradie public liability policy cover mine site work?
Often it doesn’t. Many standard tradie policies exclude mining activities or underground work. Ask your broker to confirm in writing that your policy covers your specific tasks on a mining lease.
I’m a sole trader. Do I need WorkCover?
If you have no employees, you usually don’t need WorkCover for yourself, but you also can’t claim it. Personal accident and illness insurance fills that gap. If you engage other people, check whether they count as workers.
Can I get cover if I work on coal mines?
Yes, but fewer insurers offer it and premiums can be higher. A broker with access to specialist underwriters gives you the best chance of finding suitable cover.
How quickly can I get a certificate of currency?
Once your policy is in place, a broker can usually issue a certificate the same day. Leave yourself extra time if you need specialist cover, such as underground or coal-related work.
Subscribe to our newsletter
Related posts
More Blog Posts
Mining Contractor Insurance in North Queensland: Covers, Contract Requirements and Costs
Professional Indemnity Insurance QLD: Who Needs It, What It Covers and What It Costs (2026)
Strata Insurance QLD: What Your Body Corporate Must Insure, What It Costs and How to Compare Quotes (2026)
Public Liability Insurance QLD: What It Costs, Who Needs It and Which Limit to Choose (2026)
Steel Fabricator & Manufacturing Insurance in QLD: Covers, Risks and Costs Explained
Mining Insurance in Queensland: What Mining Contractors Need to Be Covered (2026 Guide)
Is Professional Indemnity Insurance Mandatory in Australia? Requirements by Profession (QLD 2026)
Does Home Insurance Cover Flood in Queensland? Storm vs Flood vs Storm Surge Explained (2026 Guide)
Strata Insurance Townsville: Why Premiums Are High and How Body Corporates Can Reduce Them
Cyclone Season Checklist for Townsville Homeowners: Review Your Insurance Before November
What Does Public Liability Insurance Cover in Australia?
How Much Does Home Insurance Cost in Townsville, QLD?
Boat Insurance QLD: Compare Cover for Boats, Yachts & PWCs
Heavy Motor, Semi-Trailer & Trailer Insurance in Queensland

Apartment & Renters Insurance in Australia | Townsville Insurance Brokers

Landlord Insurance QLD | Landlord Policy Insurance Quote | Townsville Insurance Brokers
Caravan Insurance Australia: What It Covers, What It Costs, and How to Choose the Right Policy
Boat Insurance in QLD: Are You Really Covered?

Combined Truck & Trailer Insurance Australia | Guide

Transport Insurance: Protect Your Business in Australia

How Insurance Protects the Mining Industry from Risk and Disruption

10 Reasons to Get Commercial Truck Insurance in QLD

Truck and Trailer Insurance in Townsville: Cover Options, Costs and How to Choose


GRX25: Building Mining Connections | Townsville

Small Business Risk Management: 6 Proven Strategies to Protect Your Business

Mining Contractor Insurance: Why You Need Your Own Cover


Professional Indemnity Excess Layer Insurance for Australian Businesses


Licensed Venue Insurance in Queensland: What Pubs, Bars and Restaurants Need

Transport Insurance: Protect Your Business & Goods


Types of Business Insurance in Australia: What Your Business Actually Needs

Get In Touch With Us
Have questions about Insurance? We're here to help!