
Caravan Insurance Australia: What It Covers, What It Costs, and How to Choose the Right Policy
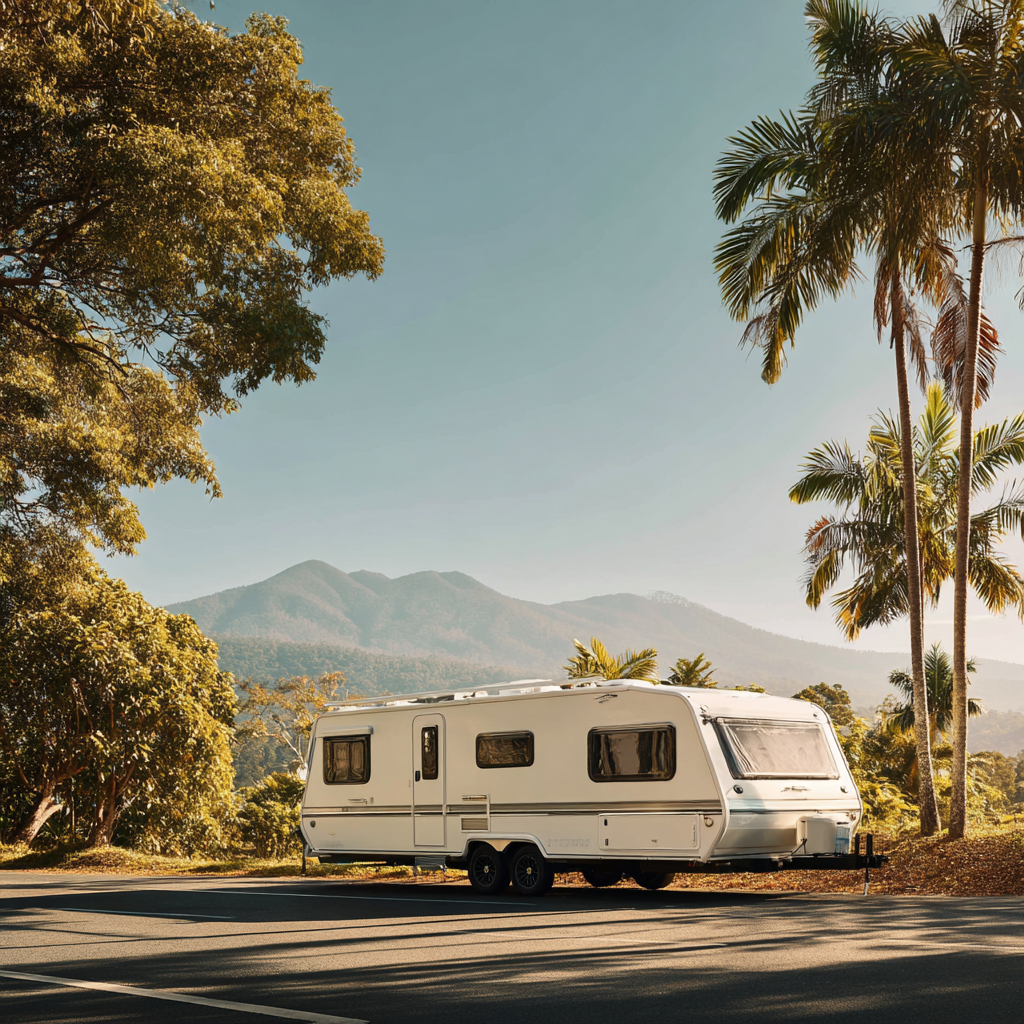
Caravanning has become one of the most popular ways for Australians to travel — with hundreds of thousands of caravans registered nationwide and millions of nights spent on the road every year. But before you hitch up and head off, it's worth understanding exactly what caravan insurance covers, what it costs, and whether you actually need it.
What Is Caravan Insurance?
Caravan insurance is a stand-alone policy that protects your caravan — and often its contents — against accidental loss or damage. It's separate from your car insurance and covers risks specific to caravans, whether you're touring, parked on-site, or storing it at home.
Unlike your vehicle's compulsory third party (CTP) cover, caravan insurance in Australia is not a legal requirement. However, if your caravan is towed and involved in an accident, your car's CTP will generally only cover injury liability — not damage to the caravan itself. That gap is exactly what caravan insurance is designed to fill.
What Does Caravan Insurance Cover?
Coverage varies between insurers, but most comprehensive caravan insurance policies in Australia include:
- Accidental damage — collision, impact, or damage caused by you or someone else
- Theft and malicious damage — including attempted theft
- Fire and explosion
- Storm, hail, flood, and cyclone cover — particularly important in North Queensland
- Legal liability cover — typically up to $20 million if your caravan damages someone else's property
- Motor burnout cover — for electrical appliances damaged by power surges
- Contents cover — for items like furniture, bedding, and kitchenware (usually capped around 1,000–2,000)
- Emergency repairs, towing, and storage costs
- Temporary accommodation — if your caravan becomes unlivable after an insured event, often $150/day up to a set limit
- New-for-old replacement — for caravans under two years old, in the case of total loss
Some insurers also offer optional extras like annexe cover, hire-out cover if you rent your caravan to others, and lay-up cover, which reduces your premium during months your caravan sits unused.
Comprehensive vs Third-Party Caravan Insurance
Like car insurance, caravan cover typically comes in three levels:
- Comprehensive — the highest level of protection, covering your own caravan for accidents, theft, storms, and more
- Third-party fire and theft — covers damage you cause to others, plus fire and theft on your own caravan
- Third-party property only — covers damage to other people's property, but nothing on your own caravan
Comprehensive cover costs more, but for most caravan owners it's the better long-term choice — especially given how expensive caravans are to repair or replace.
How Much Does Caravan Insurance Cost?
There's no single answer, since your premium depends on several factors:
- Caravan type and value — camper trailer, touring caravan, or permanent on-site van
- Age of the caravan — older vans may have different coverage terms
- How and where it's stored — secured storage generally lowers your premium
- Usage patterns — frequent touring vs occasional weekend trips
- Modifications — any changes from factory specification
- Your claims history and chosen excess
In Queensland, caravan insurance typically ranges from a few hundred dollars to over a thousand dollars annually. Choosing a higher excess can lower your premium, while adding optional extras like annexe or hire-out cover will increase it.
Cyclone, Flood and Storm Cover: Why It Matters in Queensland
If you're storing or touring with your caravan in North Queensland, storm and cyclone cover isn't optional in practice — it's essential. Caravans are more vulnerable to wind and water damage than a standard vehicle, and standard third-party policies often exclude weather events entirely. Before choosing a policy, confirm exactly what's included for cyclone, hail, and flood damage, and check whether there are seasonal exclusions or higher excess amounts during cyclone season.
5 Tips to Reduce Your Caravan Insurance Premium
- Secure your storage — locked garages or gated caravan parks often attract lower premiums than roadside parking
- Choose a higher excess if you can comfortably cover it out of pocket
- Ask about lay-up cover for months your caravan isn't in use
- Bundle policies — some brokers offer discounts when you insure your caravan alongside your car, home, or boat
- Compare providers annually — don't auto-renew without checking the market first
Why Work With a Local Townsville Broker
Comparing caravan insurance yourself can be time-consuming, and policy wording varies significantly between insurers. A local broker can:
- Explain exactly what's covered — and what isn't — in plain English
- Recommend cover suited to Queensland's cyclone and flood risk
- Handle claims on your behalf, with faster, face-to-face support
- Compare multiple insurers so you're not stuck with the first quote you receive
If you're also insuring other assets, it's worth checking your home insurance or boat insurance at the same time — bundling with one broker often makes claims and renewals simpler. Landlords or property investors travelling with a caravan part-time should also review their landlord insurance to make sure their rental property remains fully covered while they're away.
Get a Caravan Insurance Quote Today
Whether you're a weekend traveller or a full-time grey nomad, the right caravan insurance policy means one less thing to worry about on the road. To learn more about how we work, visit our about us page, or contact Townsville Insurance Brokers directly for a tailored caravan insurance quote built around how, when, and where you actually travel.
Call us at 1300 270 772 for personalised advice and a competitive quote.
Subscribe to our newsletter
Related posts
More Blog Posts
Is Professional Indemnity Insurance Mandatory in Australia? Requirements by Profession (QLD 2026)
Does Home Insurance Cover Flood in Queensland? Storm vs Flood vs Storm Surge Explained (2026 Guide)
Strata Insurance Townsville: Why Premiums Are High and How Body Corporates Can Reduce Them
Cyclone Season Checklist for Townsville Homeowners: Review Your Insurance Before November
What Does Public Liability Insurance Cover in Australia?
How Much Does Business Insurance Cost in Australia? A Complete Guide for Small Businesses
How Much Does Home Insurance Cost in Townsville, QLD?
Boat Insurance QLD: Compare Cover for Boats, Yachts & PWCs
Heavy Motor, Semi-Trailer & Trailer Insurance in Queensland

Apartment & Renters Insurance in Australia | Townsville Insurance Brokers

Landlord Insurance QLD | Landlord Policy Insurance Quote | Townsville Insurance Brokers
Caravan Insurance Australia: What It Covers, What It Costs, and How to Choose the Right Policy

Combined Truck & Trailer Insurance Australia | Guide

Truck Insurance in Australia: What You Actually Need to Know?

How Insurance Protects the Mining Industry from Risk and Disruption

10 Reasons to Get Commercial Truck Insurance in QLD

Truck and Trailer Insurance in Townsville: Cover Options, Costs and How to Choose


GRX Event 2025

Small Business Risk Management: 6 Proven Strategies to Protect Your Business

Mining Contractor Insurance: Why Contractors Arrange Their Own Cover


Professional Indemnity Excess Layer Insurance for Australian Businesses


Licensed Venue Insurance in Queensland: What Pubs, Bars and Restaurants Need

Transport sector insurance


Types of Business Insurance in Australia: What Your Business Actually Needs

Get In Touch With Us
Have questions about Insurance? We're here to help!